Grinding Media Market Size, Share, Demand & Growth Report 2026–2034
Market Overview
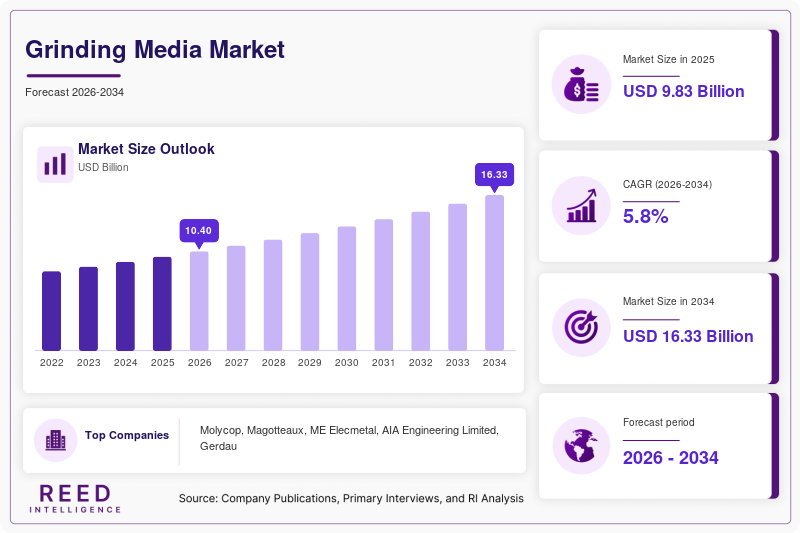
The global Grinding Media Market comprises engineered balls, rods, cylpebs, and other wear-resistant bodies used to reduce particle size and improve material-processing efficiency across mining, metallurgy, cement, power generation, chemicals, and other industrial operations. The global Grinding Media Market size is projected at USD 10.4 billion in 2026 and is expected to reach USD 16.33 billion by 2034, registering a CAGR of 5.8% during 2026–2034.
Global grinding media production exceeded 42 million tons in 2024, demonstrating the scale of demand generated by mineral processing and heavy industrial applications. Forged products represented roughly 42% of production, high-chrome cast media approximately 38%, and other grinding media around 20%.
The market is supported by expanding mining and mineral-processing activity, cement production, metals processing, and industrial power generation. Manufacturers are increasingly developing high-performance alloys, optimized diameters, improved heat-treatment processes, and application-specific media designs to improve wear life, energy efficiency, and milling performance.
Request Sample Link:
Request Sample
Grinding Media Market Size
The global Grinding Media Market size is projected at USD 10.4 billion in 2026 and is expected to hit USD 16.33 billion by 2034, with a CAGR of 5.8% during 2026–2034. Increasing mineral extraction, expansion of cement capacity, higher mineral-processing volumes, and demand for energy-efficient milling solutions are supporting market growth.
Asia Pacific dominated the market with approximately 44.3% share in 2025 and is expected to remain the leading regional market. The Middle East and Africa is projected to record one of the fastest growth rates at approximately 6.8%.
Forged Grinding Media accounted for approximately 52.4% of global revenue in 2025, supported by high impact resistance and extensive use in SAG and primary ball mills. Mining and Metallurgy represented the largest application segment at approximately 38.6% of global demand.
India is emerging as a high-growth country market, supported by expanding cement capacity, infrastructure investment, and mineral-processing activity, with growth expected at approximately 6% annually through 2034.
Grinding Media Market Trends
Shift Toward High-Performance and Data-Driven Grinding
The grinding media industry is moving from a commodity-oriented purchasing model toward performance-based product selection. Manufacturers are developing high-chrome alloys, improved forged steel grades, optimized heat-treatment processes, and application-specific media designs.
Digital mill monitoring, wear modelling, predictive analytics, and data-driven optimization are increasingly being combined with media selection to improve throughput and reduce energy consumption. High-chrome media is gaining attention in secondary milling and fine-grinding applications where corrosion, abrasion, and particle-size control are important.
Increasing Demand from Mineral Processing and Cement
Mining and metallurgy remain major sources of grinding media demand, particularly for copper, gold, iron ore, nickel, and other minerals required for infrastructure and energy-transition technologies.
Cement manufacturers are also seeking longer-lasting media to reduce maintenance and energy consumption. Emerging mineral-processing projects are increasing demand for larger SAG-mill balls and specialized grinding solutions.
Grinding Media Market Drivers
Expansion of Mining and Mineral Processing Capacity
Increasing extraction of copper, gold, iron ore, nickel, lithium, and other minerals is creating sustained demand for grinding media. Mining companies are processing increasingly complex and lower-grade ores, requiring greater comminution efficiency.
This is increasing demand for optimized media formulations, larger grinding balls, longer-wearing products, and application-specific solutions across SAG, ball, and regrind mills.
Grinding Media Market Restraints
Volatility in Steel and Energy Costs
Grinding media manufacturing depends heavily on steel, alloying materials, electricity, fuel, and transportation. Fluctuations in raw-material and energy prices can increase production costs and pressure manufacturer margins.
International trade restrictions, import duties, freight costs, and regional supply-chain disruptions can also affect grinding media availability and pricing.
Grinding Media Market Opportunities
Low-Carbon and Intelligent Grinding Solutions
Decarbonization is creating opportunities for low-carbon grinding media, recycled steel inputs, energy-efficient manufacturing, and performance optimization.
Suppliers are increasingly using laboratory testing, artificial intelligence, machine learning, and wear modelling to design media for specific ore characteristics and milling conditions. These developments can support premium product categories beyond conventional forged and cast grinding media.
Buy Now Link:
Buy Now
Challenges in Grinding Media Market
Balancing Wear Resistance, Impact Toughness, and Sustainability
Manufacturers must balance hardness and abrasion resistance with impact toughness, fracture resistance, cost, and environmental performance. Extremely hard media can provide superior wear characteristics but may create breakage risks in demanding milling circuits.
Customers are also increasingly seeking measurable carbon reductions without compromising mill stability, recovery, throughput, or operating life.
Grinding Media Market Segmentation Analysis
The market is primarily segmented by Type and Application. Forged Grinding Media held the largest type share at approximately 52.4% in 2025, while Mining and Metallurgy represented the largest application category.
Based on global production exceeding 42 million tons in 2024, forged, high-chrome cast, and other grinding media represented approximately 17.6 million tons, 16.0 million tons, and 8.4 million tons, respectively.
By Type
Forged Grinding Media
Forged Grinding Media accounted for approximately 52.4% of market revenue in 2025 and represents the dominant product category. Production is estimated at more than 18 million tons annually across global applications.
Common diameters range from approximately 25 mm to 150 mm, with mid-size products frequently used in ball mills and larger products used in SAG mills. High impact toughness, controlled hardness, and resistance to breakage make forged balls particularly suitable for hard-rock mining.
High Chrome Cast Grinding Media
High Chrome Cast Grinding Media represented approximately 30–38% of market volume, depending on application and regional mix. Global annual production is estimated at more than 15 million tons.
Chromium content commonly ranges from approximately 10% to 30%, providing high hardness and abrasion resistance. These products are widely used in secondary grinding, cement milling, and mineral-processing applications where low wear rates and dimensional stability are priorities.
Other Cast Grinding Media
Other Cast Grinding Media accounts for roughly 15–20% of market demand and includes specialized alloy and lower-chrome cast media. Annual production is estimated at approximately 8 million tons.
These products are selected where application-specific hardness, cost optimization, corrosion resistance, or mill operating conditions favor alternatives to conventional forged or high-chrome media.
By Application
Mining and Metallurgy
Mining and Metallurgy is the largest application segment, representing approximately 38.6% of market revenue and more than half of overall consumption when broader mineral-processing activity is included.
Global consumption exceeds 20 million tons annually. Copper, gold, iron ore, nickel, and other mineral-processing operations use forged and high-chrome balls across SAG, ball, and regrind mills.
Demand is increasing as mines process harder ores and invest in higher-capacity concentrators.
Cement Plant
Cement Plants represent approximately 20% of consumption, equivalent to more than 8 million tons annually.
Grinding media is used in raw-material, clinker, and finish-grinding circuits. High-chrome cast media is increasingly preferred in applications requiring lower wear, longer operating cycles, and reduced contamination.
Expanding cement capacity across Asia, the Middle East, and Africa is supporting long-term demand.
Power Plant
Power Plants account for approximately 10% of consumption, representing more than 4 million tons annually.
Grinding media is used primarily in coal pulverization and related material-processing systems. Although energy-transition policies are changing the long-term structure of coal-fired generation, existing thermal power infrastructure continues to generate replacement demand across several emerging markets.
Grinding Media Market Regional Analysis
Asia Pacific Grinding Media Market
Asia Pacific dominated the global market with approximately 44.3% revenue share in 2025. China, India, Japan, Australia, Indonesia, and Southeast Asian economies collectively drive regional consumption.
Mining and metallurgy represent the largest sector, followed by cement and industrial processing. China remains a major individual contributor because of its extensive mining, metals, cement, and manufacturing base, while India is supported by infrastructure development and expanding mineral and cement processing.
The region is expected to record strong absolute volume growth through 2034. Increasing copper, iron ore, gold, nickel, and other mineral-processing activity, together with investments in large cement plants, is supporting demand for forged and high-chrome media.
North America Grinding Media Market
North America accounts for approximately 19% of global demand, with the United States representing the largest contributor and Canada supporting demand through copper, gold, iron ore, and critical-mineral mining.
Mining and metallurgy dominate the regional sector mix, followed by cement and power applications. Increasing investment in domestic mineral supply chains is supporting replacement and expansion demand for high-performance grinding media.
Europe Grinding Media Market
Europe represents approximately 16–18% of global market revenue. Germany, France, the United Kingdom, Italy, Spain, and Nordic countries contribute through cement, metals processing, industrial minerals, and specialized manufacturing.
The regional market is increasingly focused on energy efficiency, recycling, emissions reduction, and longer-lasting media, encouraging adoption of advanced alloys and optimized grinding systems.
Latin America Grinding Media Market
Latin America contributes approximately 11% of global demand, led by Brazil, Chile, Peru, Mexico, and Argentina.
Mining and metallurgy dominate regional consumption, particularly copper, gold, iron ore, and other mineral operations. Chile and Peru are important copper-processing markets, while Brazil contributes significantly through iron ore mining and steel-related applications.
Middle East and Africa Grinding Media Market
Middle East and Africa represent approximately 8–10% of global demand and are expected to be among the faster-growing regional markets.
South Africa, Saudi Arabia, the United Arab Emirates, Ghana, and other African mining economies contribute to demand. Mining is the principal sector, while cement capacity additions across Africa and the Middle East provide an additional growth engine.
Top Players in Grinding Media Market
- Molycop
- Magotteaux
- ME Elecmetal
- AIA Engineering Limited
- Gerdau
- EVRAZ
- Scaw Metals Group
- GSI Lucchini
- Sino Grinding
- Shandong Huamin
- Goldpro New Materials
- Ningguo Dongfang Grinding Materials
- TOYO Grinding Ball Co., Ltd.
- Anhui Ruitai Materials Technology
- Jinchi Steel Ball
Recent Developments in Grinding Media Market
- January 2026: Molycop established a mineral-processing optimization and research center in Indonesia to strengthen regional technical capabilities and support high-chrome grinding media customers.
- February 2026: Molycop expanded technical training and application expertise in Chile, focusing on developments in cast grinding media and application-specific performance.
- March 2026: Molycop reported statistical validation of its 60 mm high-chrome grinding media at a South Australian copper operation, demonstrating improved wear performance against the incumbent product.
- May 2026: Molycop expanded its global wear-research capabilities with a second Wear Research Laboratory in Cikande, Indonesia, supporting standardized testing and data-driven grinding media development.
- July 2026: ME Elecmetal received recognition for its CO2Lite low-carbon grinding media initiative, highlighting a solution designed to reduce the carbon footprint of grinding media used in mining.
Grinding Media Market Segments
By Type
- Forged Grinding Media
- High Chrome Cast Grinding Media
- Other Cast Grinding Media
By Application
- Mining and Metallurgy
- Cement Plant
- Power Plant
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM

 English
 Arabic
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek