Corneal Crosslinking Devices Market Size, Share, Demand & Growth Report 2026–2034
Corneal Crosslinking Devices Market Size, Share, Demand & Growth Report 2026–2034
Market Overview
The global Corneal Crosslinking Devices Market comprises specialized ophthalmic systems used to deliver controlled ultraviolet-A (UVA) energy during corneal collagen crosslinking procedures. These devices are primarily used to stabilize biomechanically weakened corneal tissue in progressive keratoconus, corneal ectasia, and selected other corneal disorders.
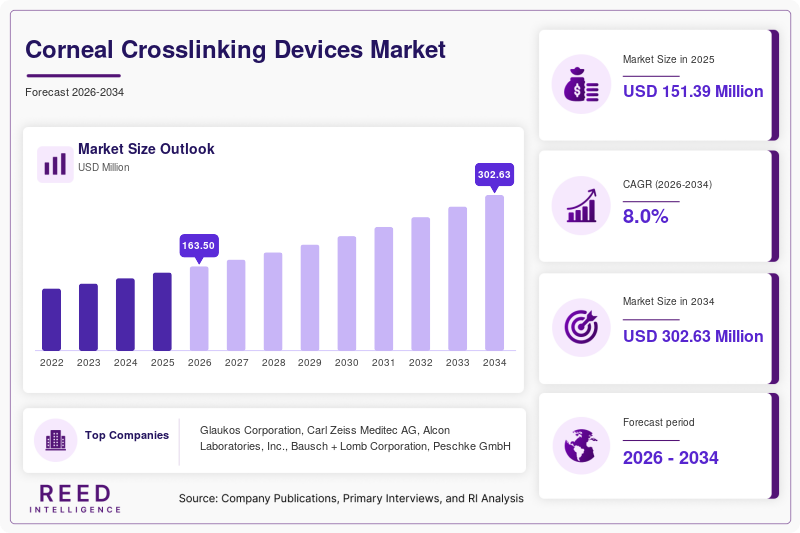
The global Corneal Crosslinking Devices Market size is projected at USD 163.5 million in 2026 and is expected to reach USD 302.63 million by 2034, registering a CAGR of 8.0% during 2026–2034. Market growth is supported by increasing diagnosis of keratoconus, wider availability of specialized ophthalmic centers, improvements in corneal imaging, and continued adoption of accelerated and epithelium-on treatment technologies.
Corneal crosslinking systems integrate controlled UVA irradiance, treatment-time management, beam uniformity, riboflavin-based photoenhancement, and increasingly oxygen-assisted treatment protocols. Based on industry estimates, approximately 0.9–1.1 million CXL procedures are performed globally each year, with keratoconus accounting for approximately 60% of procedure demand.
Request Sample Link:
Request Sample
Corneal Crosslinking Devices Market Size
The global Corneal Crosslinking Devices Market size is projected at USD 163.5 million in 2026 and is expected to hit USD 302.63 million by 2034, with a CAGR of 8.0% during 2026–2034. Rising diagnosis of keratoconus, increasing ophthalmic screening, wider availability of specialized eye-care centers, and adoption of advanced CXL technologies are supporting market expansion.
North America dominated the market with approximately 43% of global revenue in 2026, while Asia Pacific is expected to be the fastest-growing region at approximately 9% CAGR through 2034. Epithelium-off procedures remain the most established treatment configuration, while epithelium-on and accelerated crosslinking technologies are expanding rapidly.
Keratoconus represented approximately 60% of global application demand in 2026, while corneal ectasia accounted for approximately 25%. Ophthalmology clinics, specialty eye hospitals, and dedicated corneal centers represent the primary end-use settings. India is also an emerging country market and is expected to expand at approximately 10% CAGR during 2026–2034.
Corneal Crosslinking Devices Market Trends
Shift Toward Accelerated and Epithelium-On Technologies
The market is shifting from conventional epithelium-off protocols toward accelerated, pulsed-light, oxygen-enhanced, and transepithelial approaches. Accelerated systems can deliver clinically relevant energy doses in substantially shorter irradiation periods, supporting higher patient throughput and more efficient use of ophthalmic treatment facilities.
Epithelium-on technology is receiving increasing attention because it aims to preserve the corneal epithelium, reduce postoperative discomfort, and potentially shorten recovery. Product development is also focusing on supplemental oxygen, optimized riboflavin formulations, real-time treatment monitoring, and personalized treatment parameters.
Expansion Beyond Conventional Keratoconus Treatment
CXL applications are expanding beyond conventional progressive keratoconus treatment into post-refractive-surgery ectasia, selected infectious keratitis, corneal degenerative conditions, and other biomechanical disorders. Increasing integration of corneal tomography, topography, pachymetry, and digital treatment planning is supporting earlier identification of progressive disease.
The emergence of oxygen-assisted epithelium-on systems is also increasing interest in less invasive CXL workflows, particularly for younger patients and individuals who may benefit from reduced epithelial disruption.
Corneal Crosslinking Devices Market Drivers
Rising Diagnosis and Early Intervention for Keratoconus
Increasing diagnosis of progressive keratoconus is a major factor supporting market growth. Greater use of corneal topography and tomography enables ophthalmologists to identify disease progression earlier, when CXL can be used to stabilize the cornea and potentially reduce the risk of further biomechanical deterioration.
Increasing awareness among ophthalmologists, optometrists, and patients is also improving referral rates and treatment volumes. Growing screening among adolescent and young-adult populations is creating additional demand for early intervention.
Corneal Crosslinking Devices Market Restraints
High Procedure Costs and Uneven Access to Specialized Ophthalmic Care
High capital costs for advanced UVA systems, recurring costs for compatible riboflavin formulations, specialist training requirements, and variations in reimbursement can limit adoption in price-sensitive healthcare systems.
Access is also constrained in developing markets by shortages of corneal specialists and advanced diagnostic equipment. Differences in regulatory approval, clinical protocols, and reimbursement policies can further complicate international commercialization and market expansion.
Corneal Crosslinking Devices Market Opportunities
Oxygen-Assisted and Personalized Crosslinking Platforms
Next-generation epithelium-on systems, oxygen-enriched protocols, pulsed irradiation, and treatment planning based on individual corneal characteristics provide significant opportunities for market participants.
New riboflavin formulations and delivery technologies may improve stromal penetration and treatment consistency, while digital imaging and treatment algorithms can support more individualized energy delivery. Expansion into emerging markets also offers opportunities as diagnosis rates and specialist ophthalmology infrastructure improve.
Buy Now Link:
Buy Now
Challenges in Corneal Crosslinking Devices Market
Maintaining Treatment Consistency Across Diverse Corneal Conditions
Achieving predictable treatment depth, oxygen availability, riboflavin penetration, and biomechanical response remains a key technical challenge. Thin or irregular corneas may require modified treatment protocols, while differences in patient anatomy and disease severity can make standardization difficult.
Manufacturers must also demonstrate long-term safety, efficacy, device reliability, and compatibility with associated pharmaceutical formulations across multiple regulatory jurisdictions.
Corneal Crosslinking Devices Market Segmentation Analysis
By Type, Epithelium-Off systems represent approximately 40% of overall market and procedure-related demand, while Accelerated Crosslinking accounts for around 35% and Epithelium-On technologies approximately 25%.
By Application, Keratoconus dominates with approximately 60% of global demand, followed by Corneal Ectasia at approximately 25% and Other Corneal Disorders at nearly 15%.
By Type
Epithelium-Off
Epithelium-Off systems represent approximately 40% of overall market demand and remain the most established treatment configuration. An estimated 380,000–440,000 procedures annually use conventional epithelium-off workflows.
These systems typically provide controlled UVA irradiance of approximately 3–30 mW/cm², with treatment protocols designed around total fluence levels commonly near 5.4–7.2 J/cm². The approach remains widely used because of its established clinical evidence and reproducible stromal penetration.
Epithelium-On
Epithelium-On devices account for approximately 25% of market demand and are among the fastest-growing technology categories. Around 220,000–270,000 annual procedure-equivalent treatments are estimated to use or transition toward transepithelial approaches.
These systems combine specialized riboflavin formulations with UVA activation and increasingly incorporate supplemental oxygen. The technology is designed to eliminate epithelial debridement and potentially improve patient comfort and recovery while supporting effective stromal crosslinking.
Accelerated Crosslinking
Accelerated Crosslinking systems represent approximately 35% of market demand and are increasingly adopted by high-volume ophthalmic centers. An estimated 320,000–380,000 annual treatments use accelerated protocols.
Systems can employ irradiance levels of approximately 9–30 mW/cm² with substantially shorter treatment durations than traditional protocols while maintaining a predefined energy dose. Pulsed illumination, uniform beam profiles, eye tracking, and automated treatment controls are becoming increasingly important technical specifications.
By Application
Keratoconus
Keratoconus accounts for approximately 60% of global application demand and remains the core revenue-generating indication. Approximately 550,000–650,000 annual procedures are associated with progressive keratoconus.
Demand is particularly significant among adolescent and young-adult populations because early stabilization can help prevent further biomechanical deterioration. The segment is benefiting from improved diagnostic imaging and increasing acceptance of CXL as a disease-modifying intervention.
Corneal Ectasia
Corneal Ectasia represents approximately 25% of application demand, corresponding to an estimated 220,000–275,000 procedure-equivalent treatments annually.
Post-refractive-surgery ectasia is an important contributor to demand. Device requirements include precise UVA delivery and controlled treatment parameters because affected corneas can be thin and irregular. Increasing use of refractive-surgery follow-up imaging is supporting earlier identification of ectatic progression.
Other Corneal Disorders
Other Corneal Disorders contribute approximately 15% of application demand, equivalent to around 130,000–165,000 annual procedure-equivalent treatments.
This category includes emerging applications in selected infectious keratitis, corneal degenerative conditions, and other biomechanical disorders. Research into alternative photoactive agents, visible-light crosslinking, biomaterials, and non-photochemical approaches could create additional commercial opportunities through 2034.
Corneal Crosslinking Devices Market Regional Analysis
North America Corneal Crosslinking Devices Market
North America accounted for approximately 43% of global revenue in 2026, making it the largest regional market. The United States contributes the majority of regional demand, supported by established ophthalmology networks, advanced diagnostic infrastructure, specialist availability, and reimbursement development.
Hospitals, dedicated corneal centers, and ophthalmology clinics represent the principal demand channels. Technology adoption is concentrated around accelerated UVA systems, established riboflavin-based platforms, and emerging epithelium-on approaches.
Europe Corneal Crosslinking Devices Market
Europe represented approximately 25% of global market revenue in 2026, with Germany, the United Kingdom, France, Italy, and Spain representing important country markets.
The region benefits from mature ophthalmic infrastructure and extensive clinical experience with CXL. Specialized eye hospitals and private ophthalmology centers represent the largest application base, while research institutions continue to contribute to the development of advanced treatment protocols.
Asia Pacific Corneal Crosslinking Devices Market
Asia Pacific represented approximately 22% of global revenue in 2026 and is expected to record the fastest growth at roughly 9% CAGR through 2034.
China, Japan, South Korea, India, and Australia are major contributors. India and China offer significant long-term opportunities because of large patient populations, increasing ophthalmic screening, and improving access to specialized eye-care services.
Private ophthalmology chains and specialty eye hospitals are driving adoption, while lower-cost systems and accelerated treatment protocols are helping providers improve procedure capacity.
Latin America Corneal Crosslinking Devices Market
Latin America accounted for approximately 6% of global revenue in 2026, led by Brazil and Mexico. Demand is concentrated in major metropolitan ophthalmology centers.
Growth is supported by increasing diagnosis of keratoconus and gradual expansion of private healthcare infrastructure. However, reimbursement limitations, specialist availability, and equipment costs remain important considerations affecting adoption.
Middle East and Africa Corneal Crosslinking Devices Market
The Middle East and Africa accounted for approximately 4% of global demand in 2026. Saudi Arabia, the United Arab Emirates, South Africa, and selected Gulf markets represent the principal contributors.
Specialized hospitals and private eye-care centers are leading adoption. Market expansion depends on specialist training, availability of imported equipment, healthcare investment, and increasing access to advanced ophthalmic diagnosis.
Top Players in Corneal Crosslinking Devices Market
- Glaukos Corporation
- Carl Zeiss Meditec AG
- Alcon Laboratories, Inc.
- Bausch + Lomb Corporation
- Peschke GmbH
- Peschke Meditrade GmbH
- IROMED GROUP S.r.l.
- iVIS Technologies
- AJL Ophthalmic S.A.
- Sooft Italia S.p.A.
- Topcon Corporation
- NIDEK CO., LTD.
- Schwind eye-tech-solutions GmbH
- OptoQuest GmbH
Recent Developments in Corneal Crosslinking Devices Market
- February 2025: Glaukos announced FDA acceptance of the Epioxa NDA for its next-generation epithelium-on corneal crosslinking therapy, advancing the regulatory pathway for oxygen-assisted treatment.
- October 2025: The U.S. FDA approved Epioxa HD and Epioxa for epithelium-on corneal collagen crosslinking in keratoconus patients aged 13 years and older in conjunction with the O2n System and Boost Goggles.
- February 2026: Long-term clinical evidence on nurse-led accelerated CXL highlighted the potential for streamlined treatment delivery and broader use of accelerated protocols in specialist eye centers.
- March 2026: Glaukos announced commercial availability of Epioxa, expanding access to an incision-free, topical epithelium-on CXL treatment and supporting broader commercialization of oxygen-assisted technology.
- July 2026: Research developments emphasized personalized CXL, advanced riboflavin delivery, adaptive UVA activation, and emerging non-UV crosslinking technologies aimed at improving treatment precision and safety.
Corneal Crosslinking Devices Market Segments
By Type
- Epithelium-Off
- Epithelium-On
- Accelerated Crosslinking
By Application
- Keratoconus
- Corneal Ectasia
- Other Corneal Disorders
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek